Your deal model counts revenue, headcount, EBITDA, and the synergies you expect to realize.
It may not count the estate.
An acquisition can buy you a second set of everything: another website on another platform, another content system, another commerce stack, another set of customer records, and another set of reporting definitions. Not all of it makes it into the letter of intent (LOI). All of it needs an owner on day one.
Digital fragmentation is the duplication and disconnection of platforms, customer records, workflows, and reporting definitions across acquired businesses. It is not only an IT problem that surfaces after close. It is an integration cost sitting inside the target at signing, and parts of it are discoverable during diligence.
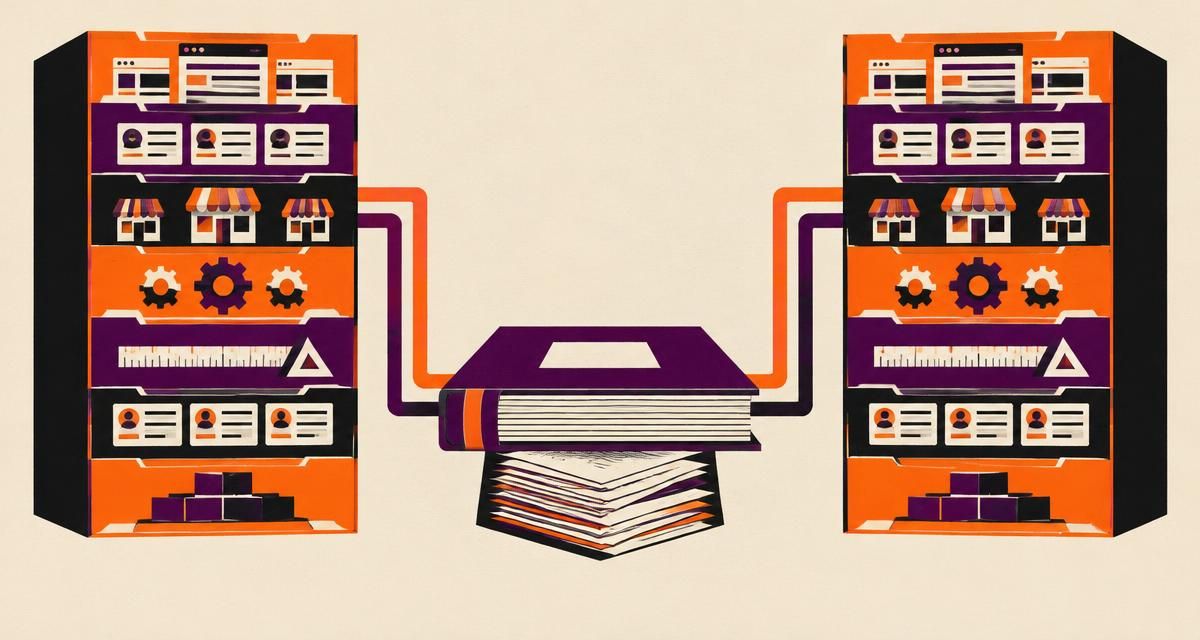
An acquired estate may arrive duplicated across seven layers:
- Presence and content: websites, content platforms, and publishing ownership.
- Discoverability: domains, redirects, and existing search equity.
- Commerce: storefronts, catalogs, and transaction journeys.
- Customer data and engagement: records, identifiers, CRM workflows, and communication history.
- Operational systems: ERP dependencies and the processes they support.
- Measurement: reporting definitions and the numbers used to compare businesses.
- Foundation: infrastructure, vendor contracts, and renewal obligations.
Every layer needs a decision. A budget for one platform is not a budget for the whole estate.
This is often treated as an IT matter, handled after close by people who were not in the deal. That framing can be expensive because it moves a priceable cost into a period when the deal team is already focused elsewhere. The same issue sits behind the digital debt hidden in a family business acquisition.
What it actually does to the model
Three effects deserve attention, and the first is the one that should worry a deal team most.
The synergy becomes difficult to verify
An acquisition thesis may depend partly on cross-sell. Verifying that synergy requires a reliable view of the customer. If the same customer exists twice, in two systems, with different identifiers or spellings, cross-sell may be happening but invisible, or not happening at all.
The board needs to know which. Otherwise, the number you underwrote becomes a number you cannot confidently defend.
In one anonymized multi-brand industrial engagement, the businesses served adjacent stages of a customer's operational needs. Cross-sell was central to the thesis, but it was tracked manually in a spreadsheet because the systems could not provide a reliable group-wide view. Our account of customer-data architecture for a multi-brand industrial group explains the integration decisions behind that problem.
The integration cost was already there when you signed
A failed implementation inside the target is a liability you inherit. The same group had attempted a CRM program that had not stuck: failed data sync, duplicate records, unclear ownership, and a sales team that stopped trusting the system and returned to spreadsheets.
Some of those are engineering problems. Lost trust is also an adoption and operating-model problem. Once it is gone, the next program may need more time and budget. New software alone does not repair it.
That history was discoverable before close. It needed to be asked about.
The cost repeats
If no repeatable capability exists for absorbing a company, the next deal can pay the same integration bill again. The work is improvised by people who are also maintaining the last integration. For a serial acquirer, that is a recurring cost that may never reach the plan.
A website consolidation de-risking strategy is one part of that capability. The wider decision is what gets standardized, what stays separate, and in what sequence the estate is integrated.
At your own exit
This cuts both ways, and it is an argument a CFO should consider.
A buyer's quality-of-earnings process may expose reporting inconsistencies that the group never reconciled. One business counting a deal at proposal and another at signature is more than a reporting quirk. It becomes a question to answer in a room where the answer can affect the transaction.
Group numbers that cannot be reconciled may lead to additional diligence, valuation pressure, or a longer close. Those are potential risks, not predictions for every transaction.
For private equity and portfolio operators, a defensible operating picture matters on both sides of the acquisition cycle: when underwriting the target and when presenting the group to a future buyer.
What to ask before you sign
A deal team does not need to wait for a technologist to ask the first questions. The answers may still require technical validation.
- Presence and content: How many content platforms exist, and who maintains each?
- Discoverability: What happens to domains and search equity if the acquired brand is retired?
- Commerce: How many storefronts and catalogs need to be maintained?
- Customer data and engagement: Has a CRM implementation been attempted before, and what happened?
- Operational systems: Is the ERP staying, and for how long?
- Measurement: Do their reporting definitions match ours?
- Foundation: Which vendor contracts transfer, and when do they renew?
All seven can change the integration estimate. The fourth is the one we would put first.
Has a CRM or platform implementation been attempted here before, and what happened to it?
A clean answer does not remove every risk, but it gives you a clearer starting point. A messy answer means you may be buying a trust problem as well as a technical one. The cost belongs in the model, not in next year's surprise.
The second question is also easy to skip. Retiring an acquired brand with incorrect redirects can put years of search equity at risk. That is existing demand the target has already invested in, not simply a website-maintenance detail.
These decisions are platform agnostic. If the estate includes HubSpot, our HubSpot implementation and integration approach and HubSpot CRM consolidation for mergers and acquisitions show how customer ownership, brand separation, and reporting decisions shape the work. A multi-brand portal strategy may mean keeping some systems separate rather than consolidating everything by default.
The point
Digital fragmentation is not only a post-close IT project. It can be an unpriced integration liability sitting inside the target at signing. Some signals are visible from outside; others need evidence from the target's teams, records, and contracts.
Groups that handle it well decide early and explicitly what happens to a company's systems when it joins. That decision turns an open-ended integration surprise into a scoped set of assumptions, dependencies, and costs.
If you are acquiring every few months and that decision has not been made, it is being made anyway. Slowly, by default, and at a price you will find out later.
Questions deal teams often ask
Is digital fragmentation the same as technical debt?
Not exactly. Technical debt can exist within a single platform. Digital fragmentation concerns the duplication and disconnection across the acquired estate, including customer identities, ownership, and reporting definitions.
Does every acquired system need to be consolidated?
No. Diligence should establish what must connect, what can remain separate, and what should be retired. Brand requirements, operational dependencies, contracts, and customer journeys shape that decision.
Can an outside-in review replace technical due diligence?
No. It can flag visible issues and improve the questions you ask. Internal system evidence, implementation history, contracts, and technical validation are still needed to scope integration reliably.
Start with the systems question
If you are acquiring at pace and the systems question keeps arriving after close rather than during diligence, talk with Sachin about your acquisition context. Start with the target's estate, the integration assumption in your model, and what you need to be able to defend.
Related reading
- The digital debt hidden in every family business acquisition.
- Designing a HubSpot-centered architecture for a multi-brand industrial group.
- Website consolidation: adding visible value without betting the whole estate.
This is a practitioner point of view based on anonymized engagement experience, not a statistical market study or legal, accounting, or valuation advice.
Bring this dispatch into a working session - one page in, scoping memo out.
Brief Foyer